Safe growth, zero market losses.
A fixed annuity guarantees your principal, credits interest tax-deferred and can pay you income for life—with the insurance company carrying the market risk.
20+ years in Deerfield Beach · Licensed Florida professionals · Hosts of Money Talks on the Blue Couch
Safe growth, zero market losses.
A fixed annuity guarantees your principal, credits interest tax-deferred and can pay you income for life—with the insurance company carrying the market risk.
20+ years in Deerfield Beach · Licensed Florida professionals · Hosts of Money Talks on the Blue Couch
Our fixed annuity strategies are
Guaranteed to Grow
Our fixed annuity strategies are
A safe place for money you cannot afford to lose
You deposit money, the insurer guarantees a minimum interest rate and the return of your principal, and—if you choose—pays you an income for the rest of your life. Fixed index contracts link interest to a market index with a floor of zero, so you participate in gains but never in losses.
Principal Protected
You are in control
- Term length: typically 3 to 10 years
- Fixed rate or index-linked crediting
- Free withdrawals of up to 10% per year
- Lifetime-income rider for you or you and your spouse
- Death benefit that bypasses probate
Tax-deferred growth. Interest is not taxed until withdrawn, so more of your money keeps compounding.
Florida guaranty protection. An additional layer of protection within statutory limits.
How they compare
Built to Protect
Lock in guarantees now and let your savings grow without ever taking a market loss.
Meet the
Fixed Index Annuity
A contract with a highly rated insurance company that guarantees your principal, credits interest linked to a market index with a floor of zero, and can pay you an income for life—tax-deferred, with no annual fees on most contracts.
Principal protected
Fixed index annuity
Bank CDs & market funds
Your principal
Guaranteed by the insurer. A down year in the index credits 0%—never a loss.
CDs: FDIC-insured. Stock and bond funds: exposed to every downturn.
Growth
Interest linked to an index, locked in each term and protected going forward.
CDs: a fixed rate. Funds: unlimited upside—and unlimited downside.
Taxes
Tax-deferred. Nothing is owed until you withdraw.
CD interest is taxed every year. Funds are taxed on dividends and gains.
Income for life
Lifetime-income option for you—or you and your spouse.
Not available. Income stops when the money runs out.
Access to funds
Typically 10% per year penalty-free, plus nursing-home and terminal-illness waivers.
CDs: early-withdrawal penalty. Funds: anytime, at whatever the market says they are worth.
Your principal
Fixed index annuity
Guaranteed by the insurer. A down year in the index credits 0%—never a loss.
Bank CDs & market funds
CDs: FDIC-insured. Stock and bond funds: exposed to every downturn.
Growth
Fixed index annuity
Interest linked to an index, locked in each term and protected going forward.
Bank CDs & market funds
CDs: a fixed rate. Funds: unlimited upside—and unlimited downside.
Taxes
Fixed index annuity
Tax-deferred. Nothing is owed until you withdraw.
Bank CDs & market funds
CD interest is taxed every year. Funds are taxed on dividends and gains.
Income for life
Fixed index annuity
Lifetime-income option for you—or you and your spouse.
Bank CDs & market funds
Not available. Income stops when the money runs out.
Access to funds
Fixed index annuity
Typically 10% per year penalty-free, plus nursing-home and terminal-illness waivers.
Bank CDs & market funds
CDs: early-withdrawal penalty. Funds: anytime, at whatever the market says they are worth.
General comparison for education only. Guarantees are backed by the claims-paying ability of the issuing insurer. Surrender charges, fees and IRS penalties may apply. Not FDIC insured. Not legal or tax advice.
Our fixed index annuities are
Made to Make Sense
Everyone’s goals look different, so we design each plan around what matters most to you.
You decide
Built around your goals
- How long the income lasts—a set period or your lifetime
- When payments start
- Single or joint life for a spouse
- Level payments or an increasing option
- How much of your principal stays accessible
Growth with a floor of zero
- Index up: you share in the gain, up to a cap
- Index down: you are credited 0% and lose nothing
- Gains lock in and become your new floor
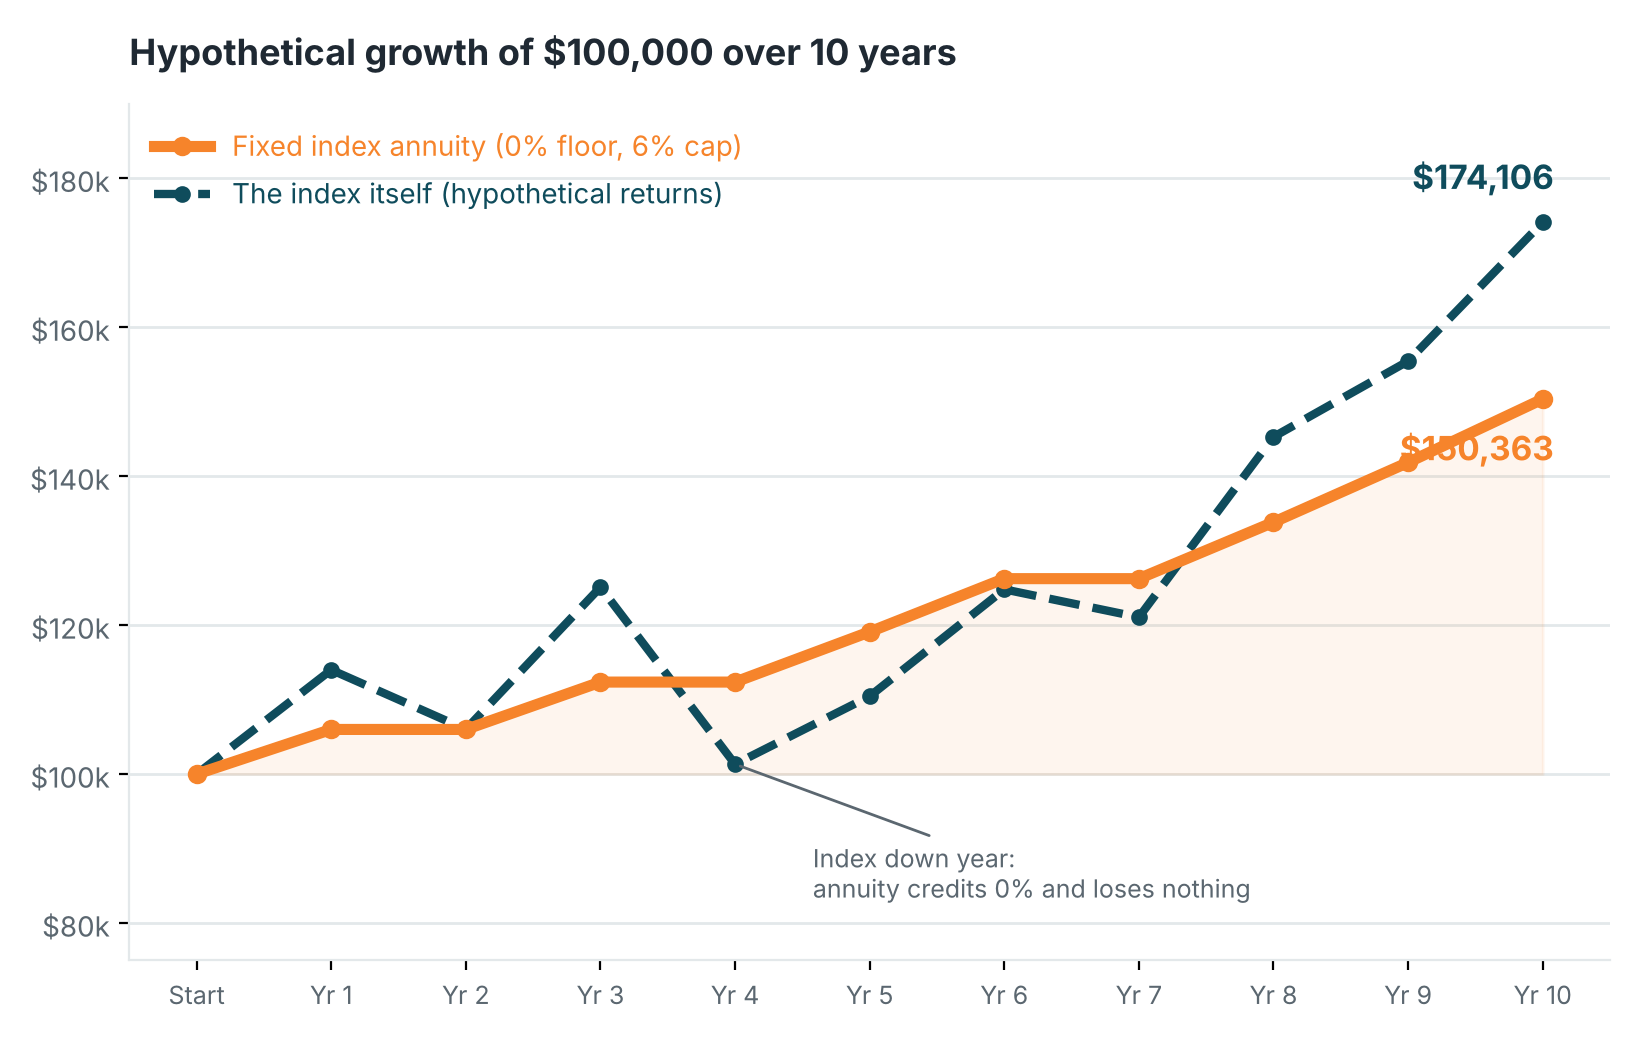
Hypothetical illustration for education only. Assumes a 0% floor and 6% annual cap on $100,000 with hypothetical index returns; actual caps, participation rates and crediting methods vary by contract and insurer.
Our fixed annuities are
Simple by Design
Principal protected
Your deposit is never reduced by a market decline. A zero year is the worst case.
Guaranteed minimum interest
A contractual floor on what you earn, declared up front.
Penalty-free access
Most contracts allow 10% annual withdrawals without surrender charges.
Income you cannot outlive
Optional riders turn the balance into a guaranteed paycheck for life.
Watch
Fixed Index Annuities 101
A short video from the Safe Money Places® Agent Network.
Free consultation = No obligation + No pressure + Plain English
Getting started is
Easy to Follow
01
Discovery conversation
We review what you have, what you need and when you need it. No products on the first visit.
02
Compare the contracts
We show the rates, caps, terms and guarantees side by side and explain the trade-offs in plain English.
03
Fund and relax
Transfer from savings, a CD, an IRA/401(k) or an old annuity. Your money is protected from day one.
Questions? We’ve got answers.
Frequently asked questions
Are fixed annuities FDIC insured?
No. Annuities are issued by insurance companies, not banks, so they are not FDIC-insured. Guarantees are backed by the claims-paying ability of the issuing insurer, and Florida maintains a Life & Health Insurance Guaranty Association as an additional layer of protection within statutory limits.
What is the difference between a fixed and a fixed index annuity?
A traditional fixed annuity credits a declared interest rate. A fixed index annuity credits interest based on the movement of a market index subject to caps or participation rates—but your principal is never reduced by a negative index year.
How is this different from a variable annuity?
With a variable annuity, your account value rises and falls with the underlying investments and you bear the risk. Most negative headlines about annuities concern variable products. Fixed and fixed index annuities are built to protect principal.
Can I get my money out?
Most contracts allow free withdrawals of up to 10% per year and waive surrender charges for nursing-home confinement or terminal illness. Withdrawals beyond the free amount during the surrender period incur charges, and withdrawals before age 59½ may be subject to a 10% IRS penalty on earnings.
How is the interest taxed?
Interest grows tax-deferred inside the contract and is taxed as ordinary income when withdrawn. We recommend reviewing withdrawals with your tax professional.
Our (real) humans are
Here to Help
Call (954) 790-5000 or email info@sunshineretire.com. We meet in Deerfield Beach or by phone.
Income for life
Personal Pension Plan
Guaranteed lifetime income for you and your spouse.
Not sure where to start? Ask us a financial question.
Every situation is different and there is no one-size-fits-all retirement plan. Ask anything—you’ll get a straight answer from a licensed professional, not a sales pitch.