20+ years in Deerfield Beach · Licensed Florida professionals · Hosts of Money Talks on the Blue Couch
MYGAs, explained
The CD alternative from an insurance company
Multi-year guaranteed annuities (MYGAs) are the simplest annuity there is: deposit, lock a guaranteed rate for the term you choose, and let the interest compound tax-deferred. No index formulas, no market exposure, no surprises.
A rate you know before you sign
The insurer declares the rate for the full term—3, 5, 7 or 10 years. It does not change with the market, and your principal is guaranteed by the carrier.
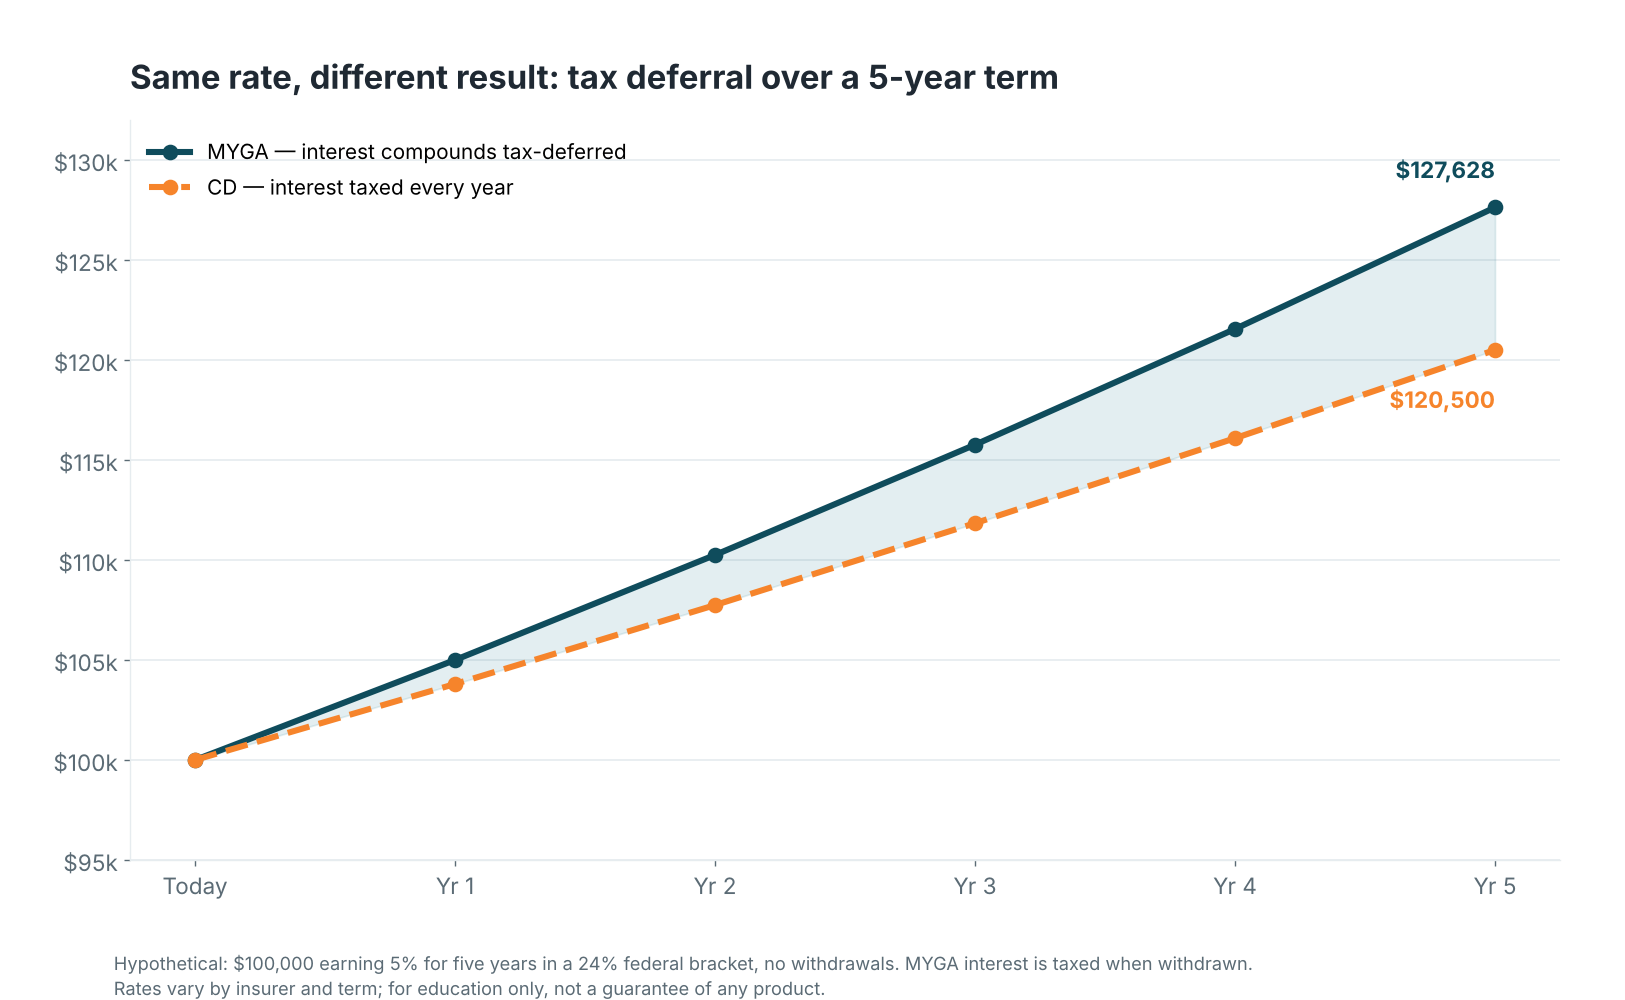
Interest is credited inside the contract and not taxed until you withdraw it, so the full balance keeps compounding. CD interest is taxed every year whether you spend it or not.
Flexible at maturity
Take the money, renew at the then-current rate, or move to another contract through a tax-free 1035 exchange. Most contracts also allow up to 10% free withdrawals each year.
Our multi-year guaranteed annuities are
Built to Grow
The same rate produces a different result when the tax bill waits until withdrawal.
Meet the
Multi-Year Guaranteed Annuity
Choose the term, lock the rate, and let interest compound tax-deferred until you need it. Principal and credited interest are guaranteed by an A-rated insurer, and most contracts allow up to 10% a year in free withdrawals.
Multi-year guaranteed annuities are insurance contracts; guarantees rest on the claims-paying ability of the issuing insurer. Surrender charges and a market value adjustment may apply to withdrawals above the free amount during the guarantee period, and withdrawals of earnings before age 59½ may be subject to a 10% IRS penalty. Not FDIC insured. Not legal or tax advice.
Side by side
MYGA vs. bank CD vs. fixed index annuity
Three safe-money tools, three different jobs.
Multi-year guaranteed annuity
Bank CD
Fixed index annuity
Rate
Guaranteed for the full term
Guaranteed for the term
Linked to an index with a 0% floor
Principal
Guaranteed by the insurer
FDIC insured
Guaranteed by the insurer
Taxes
Tax-deferred until withdrawn
Taxed every year
Tax-deferred until withdrawn
Access
Typically 10% a year penalty-free
Early-withdrawal penalty
Typically 10% a year penalty-free
Income for life
Can be converted at maturity
No
Optional lifetime-income rider
Best for
Locking a known rate for 3–10 years
Short-term savings
Growth potential with downside protection
Rate
Multi-year guaranteed annuity
Guaranteed for the full term
Bank CD
Guaranteed for the term
Fixed index annuity
Linked to an index with a 0% floor
Principal
Multi-year guaranteed annuity
Guaranteed by the insurer
Bank CD
FDIC insured
Fixed index annuity
Guaranteed by the insurer
Taxes
Multi-year guaranteed annuity
Tax-deferred until withdrawn
Bank CD
Taxed every year
Fixed index annuity
Tax-deferred until withdrawn
Access
Multi-year guaranteed annuity
Typically 10% a year penalty-free
Bank CD
Early-withdrawal penalty
Fixed index annuity
Typically 10% a year penalty-free
Income for life
Multi-year guaranteed annuity
Can be converted at maturity
Bank CD
No
Fixed index annuity
Optional lifetime-income rider
Best for
Multi-year guaranteed annuity
Locking a known rate for 3–10 years
Bank CD
Short-term savings
Fixed index annuity
Growth potential with downside protection
Multi-year guaranteed annuities are insurance contracts; guarantees rest on the claims-paying ability of the issuing insurer. Surrender charges and a market value adjustment may apply to withdrawals above the free amount during the guarantee period, and withdrawals of earnings before age 59½ may be subject to a 10% IRS penalty. Not FDIC insured. Not legal or tax advice.
Our MYGAs are
Simple by Design
Principal guaranteed
Your deposit and credited interest are guaranteed by the issuing insurer.
Term you choose
3, 5, 7 or 10 years—ladder several to keep money maturing on schedule.
Penalty-free access
Most contracts allow 10% annual withdrawals without surrender charges.
Options at maturity
Cash out, renew, or exchange tax-free into a new contract.
A fixed annuity issued by a life insurance company that credits a guaranteed interest rate for a set term—commonly 3, 5 or 7 years. Think of it as the insurance-company version of a CD, with tax deferral added.
How is a MYGA different from a bank CD?
Both pay a fixed rate for a fixed term. A MYGA’s interest compounds tax-deferred and is backed by the insurer and the state guaranty association rather than the FDIC; CD interest is taxed every year and is FDIC insured. MYGA rates have generally run above comparable CD rates.
Can I take money out during the term?
Most contracts allow a free withdrawal of up to 10% of the account value each year. Larger withdrawals during the term incur a surrender charge and may be subject to a market value adjustment.
What happens at the end of the term?
You can take the money, renew for a new term at the then-current rate, or move it into another annuity through a tax-free 1035 exchange. We put the maturity date on the calendar and review the options with you before it arrives.
Is my principal safe?
Your principal and credited interest are guaranteed by the issuing insurer. We work with carriers rated A- or better and keep each contract within Florida guaranty association limits.
What about taxes?
Interest is not taxed until withdrawn. Withdrawals of earnings before age 59½ may be subject to a 10% IRS penalty in addition to ordinary income tax, so MYGAs suit money you can leave in place for the term.
Looking for more than a fixed rate?
Other safe-money options
Higher guaranteed yield
Structured Settlements
A dated schedule of payments from an A-rated insurer, approved by a court.
Not sure where to start? Ask us a financial question.
Every situation is different and there is no one-size-fits-all retirement plan. Ask anything—you’ll get a straight answer from a licensed professional, not a sales pitch.