When you file changes everything.

When you file is the biggest retirement decision most people never analyze. Let’s analyze it.
20+ years in Deerfield Beach  ·  Licensed Florida professionals  ·  Hosts of Money Talks on the Blue Couch

When you file changes everything.

When you file is the biggest retirement decision most people never analyze. Let’s analyze it.
20+ years in Deerfield Beach  ·  Licensed Florida professionals  ·  Hosts of Money Talks on the Blue Couch
Social Security basics

A benefit you cannot outlive—if you claim it wisely

You cannot outlive Social Security, it adjusts for inflation, and it arrives without any investment decisions on your part. The catch: the decisions you make before you file are permanent, and the wrong one can cost a couple well into six figures over a retirement.

Your filing date, analyzed

Full Retirement Age, what early or delayed filing really costs, and how the choice interacts with your other income. We run the numbers for your situation, not a rule of thumb.
Spousal, survivor and ex-spouse benefits

Married, widowed or divorced after a 10-year marriage? Rules most people never hear about can change the best filing strategy for a household.

Taxes and the earnings test

Up to 85% of your benefit can be taxable, and working before Full Retirement Age can temporarily reduce it. Coordinating withdrawals from other accounts keeps more of the check.
The claiming decision

Built Around Timing

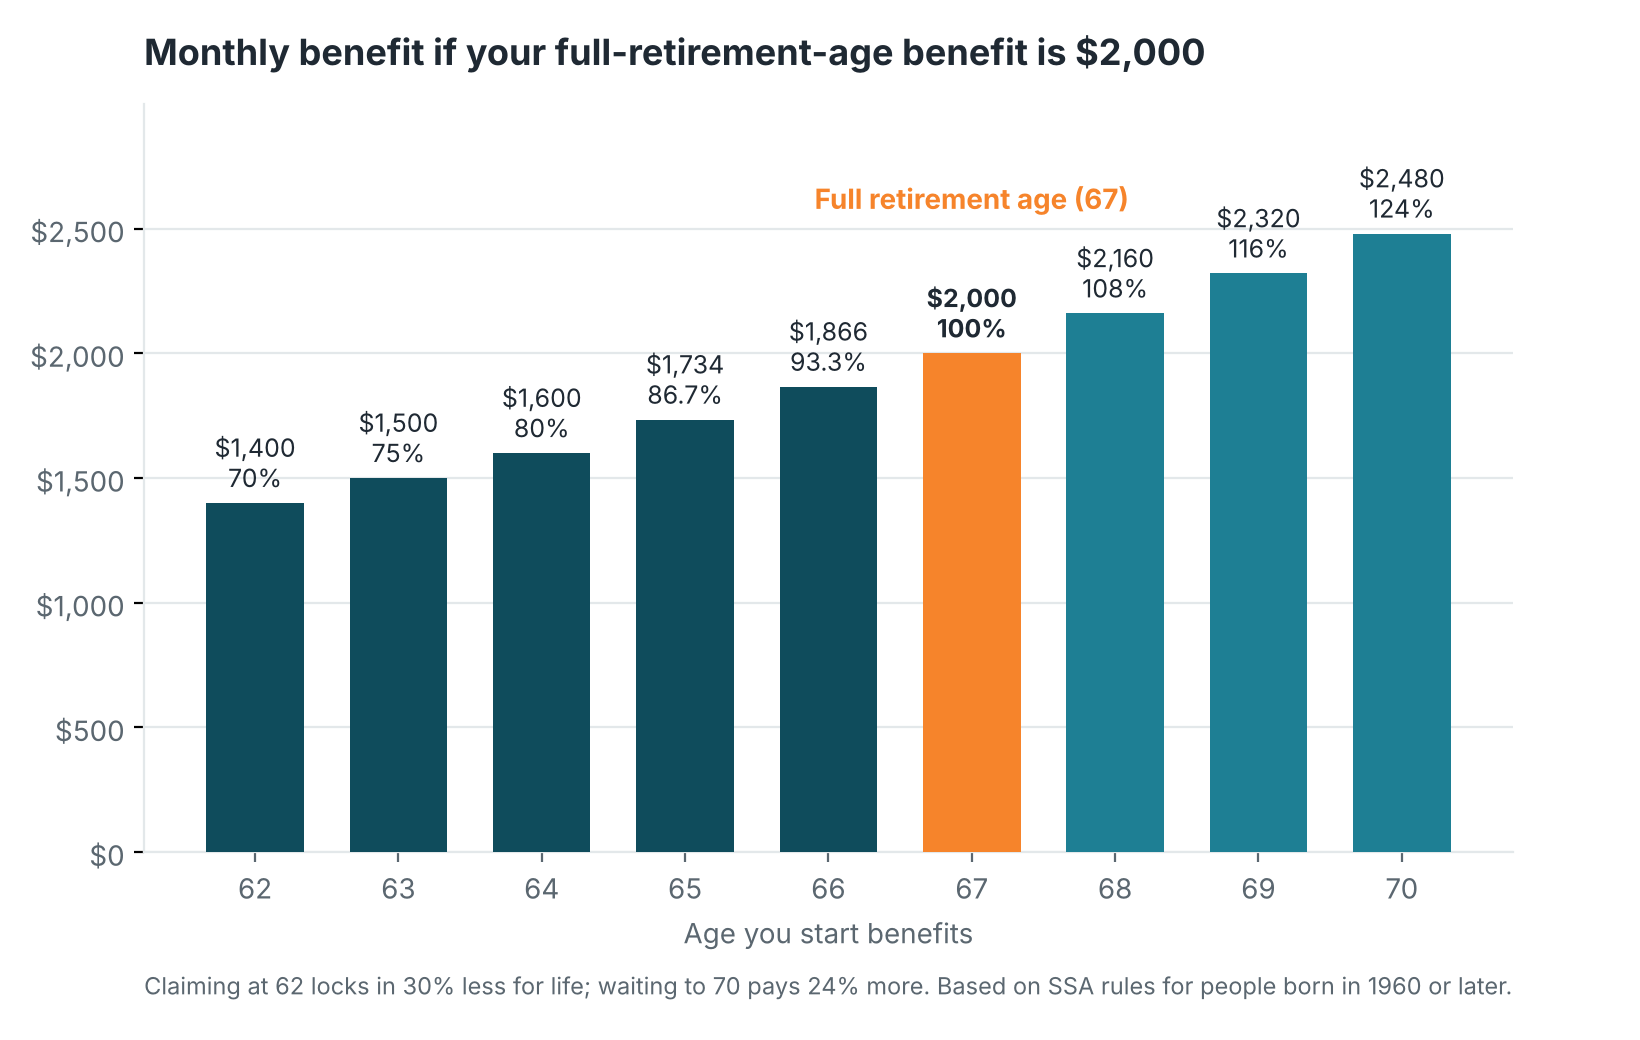
The month you file sets your benefit for life. Here is what the choice looks like for someone whose full-retirement-age benefit is $2,000.
Get your

Social Security Review

We run your actual earnings record through the claiming math—early, full and delayed filing, spousal and survivor options, taxes and the earnings test—and show the lifetime difference in plain English.
Free review
Claim at 62
Claim at 67 (FRA)
Claim at 70
Monthly benefit
$1,400 — 70% of full
$2,000 — 100%
$2,480 — 124% of full
Permanent?
Yes—the reduction lasts for life
Yes
Yes—the increase lasts for life
Earnings test
Applies until FRA
None
None
Survivor benefit for a spouse
Based on the reduced amount
Based on the full amount
Based on the increased amount
Often fits
Health concerns or no other income
A balanced plan
Longevity in the family and other income to bridge the gap
Monthly benefit
Claim at 62
$1,400 — 70% of full
Claim at 67 (FRA)
$2,000 — 100%
Claim at 70
$2,480 — 124% of full
Permanent?
Claim at 62
Yes—the reduction lasts for life
Claim at 67 (FRA)
Yes
Claim at 70
Yes—the increase lasts for life
Earnings test
Claim at 62
Applies until FRA
Claim at 67 (FRA)
None
Claim at 70
None
Survivor benefit for a spouse
Claim at 62
Based on the reduced amount
Claim at 67 (FRA)
Based on the full amount
Claim at 70
Based on the increased amount
Often fits
Claim at 62
Health concerns or no other income
Claim at 67 (FRA)
A balanced plan
Claim at 70
Longevity in the family and other income to bridge the gap
Based on Social Security Administration rules for people born in 1960 or later (full retirement age 67). Illustration uses a $2,000 full-retirement-age benefit; your amounts will differ. Sunshine Financial Partners is not affiliated with the SSA.
Every year you wait

Adds Up for Life

Delayed-retirement credits are one of the few guaranteed, inflation-adjusted raises available to retirees.
Bridge the gap

Delay without going without

Waiting to 70 can mean living on savings for a few years. A Personal Pension Plan or a short-term fixed annuity can bridge those years with guaranteed income, so the higher check is affordable.

Benefit by claiming age

Based on Social Security Administration rules for people born in 1960 or later (full retirement age 67). Illustration uses a $2,000 full-retirement-age benefit; your amounts will differ. Sunshine Financial Partners is not affiliated with the SSA.
Fill the gap

Social Security is one leg of the stool

For most retirees it replaces a quarter to a half of pre-retirement income. The Personal Pension Plan fills the rest with guaranteed income.
Fill the gap

Social Security is one leg of the stool

For most retirees it replaces a quarter to a half of pre-retirement income. The Personal Pension Plan fills the rest with guaranteed income.
Free consultation  =  No obligation  +  No pressure  +  Plain English
Questions? We’ve got answers.

Frequently asked questions

For anyone born in 1960 or later, Full Retirement Age (FRA) is 67. Those born 1955–1959 have an FRA between 66 and 2 months and 66 and 10 months.
Filing at 62 permanently reduces your benefit by up to 30%. Waiting past FRA earns delayed-retirement credits of 8% per year until age 70.
Yes, but before FRA an earnings test temporarily withholds $1 of benefits for every $2 earned above an annual limit. After FRA there is no earnings limit.
Up to 85% of your benefit can be taxable depending on your combined income. Coordinating withdrawals from other accounts can reduce the tax.
No. Our Social Security education is provided through the Council of Financial Educators (COFE), a 501(c)(3) nonprofit. Final benefit determinations are made only by the Social Security Administration.

Not sure where to start? Ask us a financial question.

Every situation is different and there is no one-size-fits-all retirement plan. Ask anything—you’ll get a straight answer from a licensed professional, not a sales pitch.
Scroll to Top